ACER's Latest News - 8 November 2026

New ACER guidance helps market participants comply with revised REMIT data reporting rules

Today, ACER publishes the first set of its revised REMIT data reporting guidance, providing policy and technical instructions on how to report wholesale energy market data to ACER.

REMIT is the EU-wide framework that detects and deters market manipulation and abuse in wholesale energy markets, enhancing transparency and trust in the integrity of Europe’s energy markets.

What's next at ACER? Have a look at our upcoming events and public consultations.

Not yet registered to ACER's Latest News? Subscribe for free.

Interested to work at ACER? Check out our vacancies.

Any questions? Reach out to us at info@acer.europa.eu.

New ACER guidance helps market participants comply with revised REMIT data reporting rules

Image
Light bulb and data trends on open book
Intro News
ACER publishes the first set of its revised REMIT data reporting documents, providing policy and technical instructions on how to report wholesale energy market data.

New ACER guidance helps market participants comply with revised REMIT data reporting rules

What is it about?

Today, ACER publishes the first set of its revised REMIT data reporting documents, providing policy and technical instructions on how to report wholesale energy market data to ACER.

REMIT is the EU-wide framework that detects and deters market manipulation and abuse in wholesale energy markets, enhancing transparency and trust in the integrity of Europe’s energy markets.

What’s changing?

Following the revision of REMIT (2024) and of its secondary legislation (2026), new data reporting requirements will be introduced in three phases between October 2027 and July 2028. To help market participants and other reporting parties meet their new obligations, ACER is updating its guidance in three sets, one per phase. 

This first set covers exposure and continuous reporting, LNG market data and bilateral transactions with energy intensive consumers. The corresponding first-phase requirements will apply from 29 October 2027. Until then, reporting continues as under the current framework and existing guidance.

What’s in this first set of guidance? 

Together, these documents give reporting parties a clear, practical basis to prepare for the new requirements and report consistently across the EU. They were developed in consultation with stakeholders, national regulatory authorities (NRAs) and the European Commission.

What’s next? 

Any questions?

ACER is collecting questions ahead of its webinar (23 November). Submit your questions by Monday 16 November 2026.

For technical queries or specific reporting situations, contact us at REMIT Query Form, as these will not be covered during the webinar.

ACER webinar: New REMIT data reporting guidance

Online
23/11/2026 10:00 - 11:30 (Europe/Brussels)

Event banner

ACER's Latest News - 8 November 2026

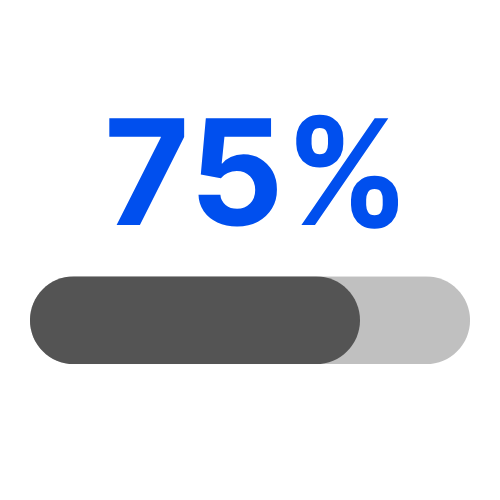
EU gas storage is 75% filled

In summer 2026, disruptions to liquefied natural gas (LNG) flows

What's next at ACER? Have a look at our upcoming events and public consultations.

Not yet registered to ACER's Latest News? Subscribe for free.

Interested to work at ACER? Check out our vacancies.

Any questions? Reach out to us at info@acer.europa.eu.

EU gas storage is 75% filled

Image
Gas pipeline
Intro News
ACER’s latest gas Monitoring Report looks at developments during the 2026 gas summer season and what they could mean for security of supply in winter 2026-2027.

EU gas storage is 75% filled

What is it about?

In summer 2026, disruptions to liquefied natural gas (LNG) flows linked to the conflict in the Middle East, low gas storage levels after winter 2025-2026 and slower refilling contributed to tighter supply and pushed the EU’s gas prices higher.

ACER’s latest gas Monitoring Report looks at developments during the 2026 gas summer season and what they could mean for security of supply in winter 2026-2027.

What trends did ACER’s monitoring find?

  • EU gas stocks remain below historical levels after a slow summer refill. At the end of winter 2025-2026 underground gas storage levels reached 28% of capacity, down from 34% a year earlier. By 21 October 2026, EU storage stood at 75%.

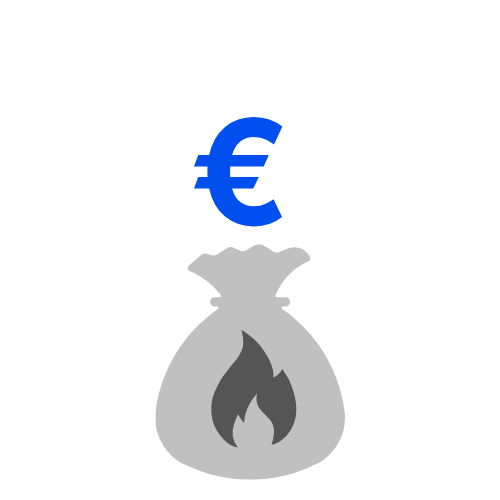
  • Refilling storage has become more expensive. The upper bound estimated cost of refilling storage in 2026 reached €27 billion, while the average cost of injected gas was the second highest in the past decade. The conflict in the Middle East contributed to higher gas prices.

  • EU reliance on US LNG continued to grow, as Qatari and Russian supplies fell. US LNG now accounts for around 30% of total EU gas supply, and total Russian gas around 11%. Russian LNG imports are 2% lower than in summer 2025, while Russian pipeline imports fell by 3%. The total EU LNG imports fell by 14%. No significant volumes of Qatari LNG reached the EU in summer 2026. 

  • Gas prices rose as Europe competed for LNG in a tighter global market. Spot EU hub prices closed to near EUR 90/MWh mid-October 2026.

  • The Middle East conflict added an estimated €18-33 billion to Europe’s gas import bill for the same quantity of gas. These additional costs are spread across the gas value chain, affecting household and industrial consumers and driving up electricity prices. Disrupted Qatari exports through the Strait of Hormuz increased EU reliance on other suppliers, especially the USA.

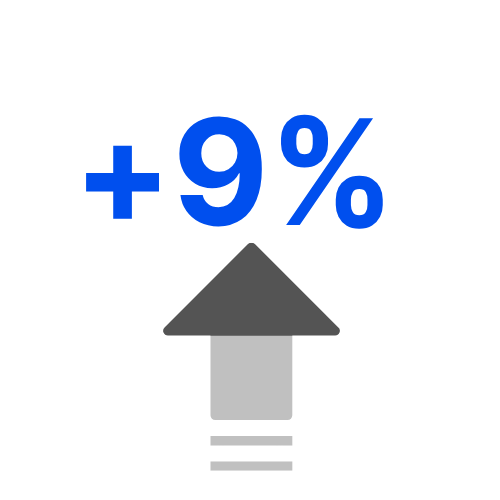
  • Hot weather and droughts during summer increased demand for gas-fired power generation. Gas generation rose by nearly 9% over the gas summer period and by 20% in August compared to the same period in 2025.

Looking ahead

  • A tighter winter supply balance: The EU will enter the winter with lower overall storage levels than the nine-year average. Gas demand is around 20% lower since the 2022 gas crisis, increasing the relative value of current storage levels. Weather-driven demand will be impacting the gas storage stocks' evolution.

  • The EU is expected to continue to face international competition for securing LNG imports: The EU and Asia will continue to compete for flexible spot LNG cargoes during the heating season, possibly increasing exposure to price pressure and volatility. 

  • The EU's winter prospects may lead to higher LNG needs: The actual level of LNG imports needed will ultimately depend on, inter alia, the severity of the winter weather and gas demand. In the current context, additional LNG imports are mainly to come from the USA in view of reduced Qatari supply and the Russian LNG phase-out from January 2027.

EU electricity market integration

  • Electricity
Image
Solar panels

2026 Monitoring Report

The integration of electricity markets across the EU is central to achieving a secure, affordable and sustainable energy system. Cross-border trade increases competition, improving affordability for consumers. An integrated EU electricity market supports more renewables, strengthens security of supply through resource sharing and improves system resilience. 

Over the past decade, market integration has made substantial progress, with multiple projects delivered. However, significant benefits of market integration remain untapped due to implementation challenges. 

This ACER Monitoring Report examines the progress of EU electricity wholesale market integration and its benefits. It covers key developments across all market timeframes (forward, day-ahead, intraday, balancing), as well as development in cross-zonal capacity availability and congestion management.

What trends did ACER's monitoring find?

ACER's monitoring finds progress: 

  • Cross-border trade generates about €32 billion in economic surplus each year in the day-ahead market alone. Further integration over all markets could deliver at least an additional €4 billion per year.
  • Day-ahead trading has largely moved to 15-minute products. Introduced on 1 October 2025 to better reflect rapidly changing system conditions, they now account for almost 90% of all electricity traded in the day-ahead market. 
  • Market participants are trading closer to real time. Since January 2026, cross-zonal intraday trading has been possible up to 30 minutes before delivery on some borders. Around 20% of these trades now take place in the final hour before delivery, allowing market participants to adjust their positions closer to real-time.
  • Balancing market integration delivers significant benefits. European balancing platforms generated over €1 billion in economic surplus in 2025 alone. Regional cooperation in balancing capacity procurement has also delivered substantial benefits by reducing costs and enabling more reserve needs to be met.
  • Interest is growing in pairing renewables with storage. Power purchase agreements (long-term contracts between sellers and buyers) increasingly combine renewable generation with energy storage, supporting investment in renewable energy and increasing flexibility.

However, significant challenges remain:

  • Forward market liquidity remains concentrated in a few bidding zones and trading activity falls rapidly for electricity contracts traded beyond one year-ahead. 
  • Price differences between bidding zones are widening, increasing the importance of making sufficient transmission capacity available for cross-zonal trade. 
  • The availability of cross-zonal capacity is still lagging. The requirement to make at least 70% of capacity available for trading across borders is not yet fully implemented throughout the EU. Markets that operate closer to real time, such as intraday and balancing markets, are particularly affected by limited access to cross-zonal trade.
  • The cost of managing grid congestion is rising, up from €4.3 billion in 2024 to €5.4 billion in 2025, with a growing share linked to voltage control following the Iberian blackout. Beyond the cost to network users, physical congestion also results in the curtailment of renewables.

Where could further progress bring benefits?

ACER's analysis points to several areas where further work could help unlock these benefits:

  • Speed up delayed market integration projects. They could have delivered an economic surplus of approximately €700 million in 2025 had they been implemented on time.
  • Reform the framework for long-term transmission rights, so market participants in less liquid bidding zones can have access to equally effective hedging possibilities. 
  • Design public support schemes to minimise market distortions, for example by encouraging electricity producers to reduce renewable generation when prices are negative.
  • Ensure cross-zonal capacity is maximised, including by fully applying the 70% minimum capacity requirement and implementing flow-based allocation closer to real time. In the Core capacity calculation region alone, flow-based allocation in intraday auctions could have generated over €460 million in economic surplus in 2025.
  • Secure voltage control resources through efficient and competitive processes, as violations of voltage limits in the network are becoming increasingly common. 
  • Complete the accession of all transmission system operators to the European balancing platforms, expand balancing capacity cooperation, and facilitate participation of new flexibility resources (such as batteries or demand response) in balancing services.

Looking ahead

Market integration already brings clear benefits, but its full value has yet to be realised. As renewable generation grows, cross-zonal trading, particularly close to real time, will become increasingly valuable. Further integration and the full application of existing rules, such as the minimum 70% requirement, would deliver significant gains for consumers in the coming years.

Highlights

  • €7 billion

    yearly benefits from selected market integration projects.

  • €5.4 billion

    cost of managing grid congestion in 2025 (up from €4.3 billion in 2024).

  • 95%

    reduction of hours with balancing energy prices for automatic frequency restoration reserve exceeding ±7,500 EUR/MWh.

Report

ACER's 2026 Monitoring Report on the progress of EU electricity wholesale market integration:

  • analyses the benefits of market integration in the EU;
  • examines recent developments in long-term, day-ahead, intraday and balancing markets;
  • tracks progress in maximising cross-zonal capacity; 
  • explores how congestion management needs and costs evolved in 2025; and
  • estimates the potential benefits of extending day-ahead market coupling to the Energy Community Contracting Parties.

  Access the report

Infographic

Interested in the main highlights of the report?

  Dive into our infographic

Dashboard

The electricity market dashboard complements the Monitoring Report with more detailed data and analysis on EU market integration. It follows the structure of the report and covers:

  • long-term markets;
  • day-ahead and intraday markets;
  • balancing markets; and
  • congestion management.

Users can filter interactive figures by time span, data granularity, geographical scope, market segment and product or indicator.

  Access the dashboard.

Additional Information

No

Key developments in European gas wholesale markets - summer 2026

  • Gas
Image
Gas pipeline

2026 Monitoring Report

The EU’s gas wholesale market continues to manage changing supply patterns, with liquefied natural gas (LNG) playing an important role in balancing supply and demand and securing gas flows across the EU.

In summer 2026, these dynamics came under renewed pressure. Disruptions to LNG flows linked to the conflict in the Middle East, low storage levels after winter 2025-2026 and slower refilling contributed to tighter supply and pushed the EU’s gas prices higher.

ACER’s Monitoring Report looks at these summer developments and what they could mean for security of supply in winter 2026-2027. 

What trends did ACER monitoring find?

  • EU gas stocks remain below historical levels after a slow summer refill. At the end of winter 2025-2026 underground gas storage levels reached 28% of capacity, down from 34% a year earlier and below the 9-year average of around 40%. The slower filling pace reflected, inter alia, higher LNG import prices and weak commercial interest for summer injection. By 21 October 2026, EU storage stood at 75%. 
  • Refilling storage has become more expensive. The upper bound estimated cost of refilling storage in 2026 reached €27 billion. While below the roughly €100 billion spent during the 2022 energy crisis, the average cost of injected gas was the second highest in the past decade. The conflict in the Middle East contributed to higher gas prices.
  • EU reliance on US LNG continued to grow as Qatari and Russian supplies fell. US LNG now accounts for around 30% of total EU gas supply, and total Russian gas around 11%. Russian LNG imports are 2% lower than in summer 2025, while Russian pipeline imports fell by 3%. The total EU LNG imports fell by 14%. No significant volumes of Qatari LNG reached the EU in summer 2026. 
  • Gas prices rose as Europe competed for LNG in a tighter global market. Spot EU hub prices closed to near EUR 90/MWh mid-October 2026, with unfavourable winter-summer price spreads and competition with Asia for spot LNG. 
  • The Middle East conflict added an estimated €18-33 billion to Europe's gas import bill for the same quantity of gas. The range depends on whether day-ahead TTF prices or TTF monthly prices are used. These additional costs are spread across the gas value chain, affecting household and industrial consumers and driving up electricity prices. Disruption to Qatari LNG exports through the Strait of Hormuz increased EU reliance on other suppliers, especially the USA.
  • Hot weather and droughts during summer increased demand for gas-fired power generation. Consecutive heatwaves, hotter rivers and lower water flow levels constrained nuclear and hydro generation. The strong growth in solar power responded to higher electricity demand, yet the reduced nuclear and hydro output increased gas-fired and coal generation. Gas generation rose by nearly 9% over the gas summer period and by 20% in August compared to the same period in 2025.

Looking ahead

  • A tighter winter supply balance: The EU will enter the winter with lower overall storage levels than the nine-year average. Gas demand is around 20% lower since the 2022 gas crisis, increasing the relative value of current storage levels. Weather-driven demand will be impacting the gas storage stocks' evolution.
  • The EU is expected to continue to face international competition for securing LNG imports: The EU and Asia will continue to compete for flexible spot LNG cargoes during the heating season, possibly increasing exposure to price pressure and volatility. 
  • The EU's winter prospects may lead to higher LNG needs: The actual level of LNG imports needed will ultimately depend on, inter alia, the severity of the winter weather and gas demand. In the current context, additional LNG imports are mainly to come from the USA in view of reduced Qatari supply and the Russian LNG phase-out from January 2027.

Highlights

  • As of 21 October, EU gas storage was 75% full, below the nine-year average.

  • EU heatwaves and a hotter-than-average summer drove a 9% increase in gas demand for power.

  • The Middle East conflict added an estimated €18-33 billion to Europe's gas import bill. 

Report

ACER’s Monitoring Report on key developments in European gas wholesale markets covers the 2026 gas summer season and looks ahead to winter 2026-2027. It analyses:

  • underground gas storage developments and their implications for security of supply;
  • the impact of the Middle East conflict on the EU gas market;
  • market fundamentals and price developments; and
  • gas flows and market integration across the EU.

  Access the report

Additional information

No

ACER webinar: Assessing EU-wide flexibility needs with open-source modelling

ACER's Latest News - 30 October 2026

ACER seeks feedback on its preliminary model for assessing electricity flexibility needs in the EU

On 5 November 2026, ACER will open a public consultation on the preliminary version of EU-Flex, an open-source electricity market model developed to assess flexibility needs across the EU.

What's next at ACER? Have a look at our upcoming events and public consultations.

Not yet registered to ACER's Latest News? Subscribe for free.

Interested to work at ACER? Check out our vacancies.

Any questions? Reach out to us at info@acer.europa.eu.
ACER seeks feedback on its preliminary model for assessing electricity flexibility needs in the EU

Image
Battery storage and renewables
Intro News
On 5 November 2026, ACER will introduce the preliminary version of EU-Flex, an open-source electricity market model developed to assess flexibility needs across the EU.

ACER seeks feedback on its preliminary model for assessing electricity flexibility needs in the EU

What is it about?

On 5 November 2026, ACER will open a public consultation on the preliminary version of EU-Flex, an open-source electricity market model developed to assess flexibility needs across the EU.

Electricity flexibility is the power system’s ability to respond to changes in supply and demand. Under the EU’s Electricity Market Design reform (2024), ACER is tasked with estimating flexibility needs across the EU and identifying potential gaps.

The first assessment is planned for July 2027, with the EU-Flex model supporting this process.

Why consult?

Stakeholders will have the opportunity to explore the proposed modelling approach ahead of the 2027 assessment.

The preliminary release of EU-Flex will include:

  • An explanatory paper introducing the model and demonstrating its use through a test case.

  • The preliminary model, including its source code and test case input data.

  • A document describing the underlying methodology.

The consultation will help ACER gather feedback on the model and its methodology, as well as identify potential gaps, limitations and areas for improvement.

Get involved!

The public consultation will run from 5 November to 17 December 2026.

On 17 November 2026, ACER will hold a webinar to present the model, explain its key features and demonstrate how to run it. Register for free.